More investments
Fix your credit with AI and turn it into funding in 30 days.
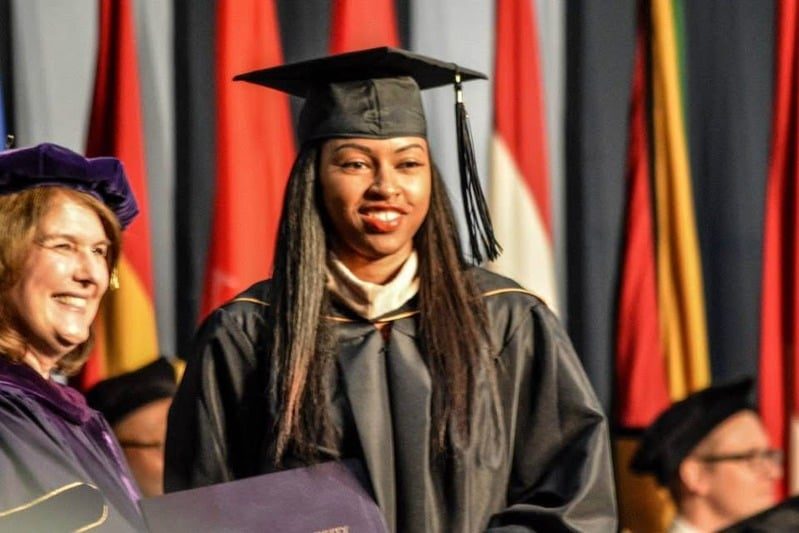
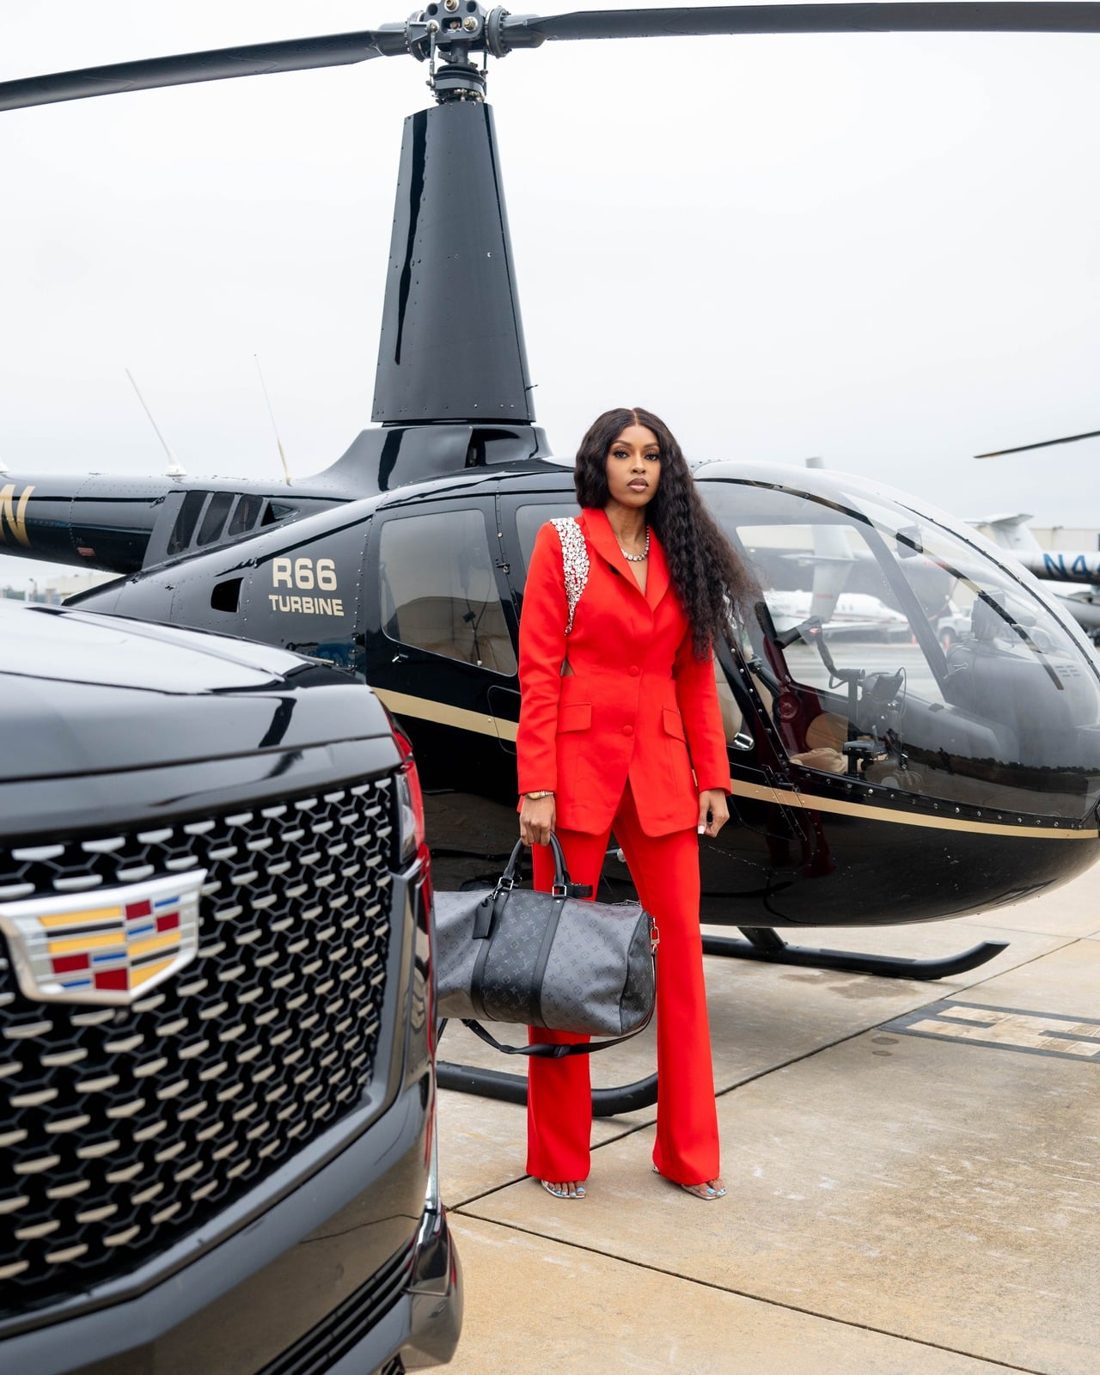
Sacrifice
Success
How faith built my fortune
More freedom. More experiences. More possibilities.
You are not behind because you're not smart. You're behind because nobody ever exposed you to this room, these tools, this language.
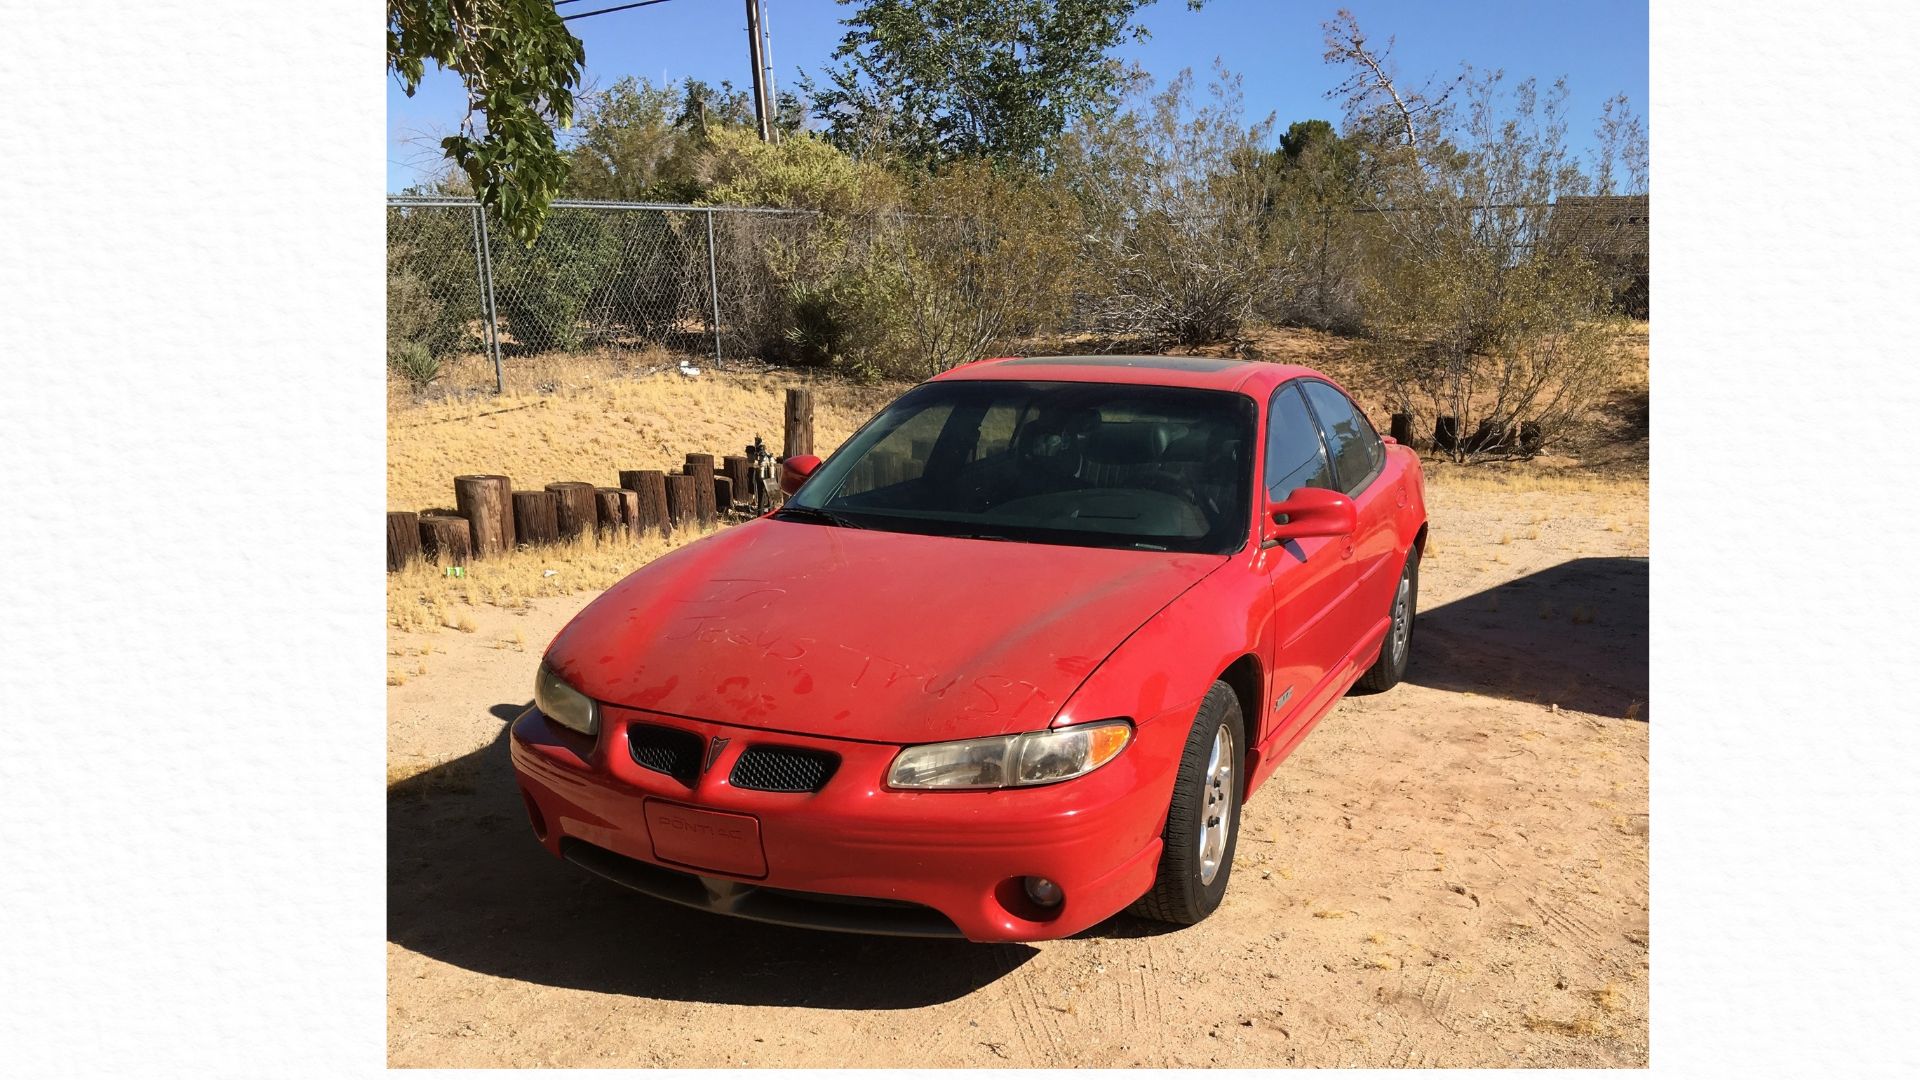
The room. The early chapter. The car. This is where her transformation began.
God didn't bring me this far to keep it to myself
The same faith and strategy combo that took me from a 567 to a 750 is the exact system I'm handing you today.
Old way: hire a company, $99 a month for 6 months, hope it works. New way: Claude does it, free, in one afternoon.
TransUnion, Experian and Equifax in one report. That PDF is what you hand to Claude in step 2.
You are a FICO-trained credit analyst. I'm attaching my full 3-bureau credit report.

TASK: Analyze the report and list EVERY negative item hurting my score: delinquencies, charge-offs, collections, repossessions, late payments, and high-utilization accounts.

For each item, give me:
- Creditor name & account number (last 4)
- Balance & original balance
- Status & date reported
- Which bureau(s) are reporting it (TransUnion / Experian / Equifax)
- Estimated point impact on my FICO
- Priority score (1 = kill first, 5 = leave for later)

Present it as a clean, ranked table. Then give me a 3-sentence summary of the fastest wins I can attack in 30 days.
Based on the credit report analysis above, draft 3 professional dispute letters: one addressed to TransUnion, one to Equifax, one to Experian.

Each letter must:
1. Be dated today and include MY address at the top and the bureau's address below.
2. Cite these specific FCRA violations:
   - 15 U.S.C. § 1681e(b): duty of maximum possible accuracy
   - 15 U.S.C. § 1681i(a): reinvestigation requirement
   - 15 U.S.C. § 1681s-2: furnisher accuracy duty
3. Demand deletion per 15 U.S.C. § 1681i(a)(5) within 30 days.
4. Organize disputes by category: Personal Information, then Accounts, then Inquiries.
5. For each disputed item include: creditor name, account number, reason for dispute (inaccurate / unverifiable / outdated), and the specific statute violated.
6. Close with a demand for written confirmation and escalation to the CFPB, Attorney General, and FTC if unresolved.

Use formal, firm legal tone. No fluff. Output all 3 letters ready to print.
You are a credit-dispute specialist with deep expertise in the Fair Credit Reporting Act (FCRA) and Uniform Commercial Code (UCC).

Input: [paste the items the bureau came back as "verified"]

Your tasks:
  1. Identify every flagged item that is inaccurate, outdated, or unverifiable.
  2. Analyze each under FCRA and relevant UCC provisions — cite specific sections (e.g., 15 U.S.C. § 1681i(a)(1)(A), UCC § 3-501).
  3. Draft a round-2 dispute letter for each item that:
      • References the statute(s) violated
      • Explains why the item must be removed
      • Demands method of verification per 15 U.S.C. § 1681i(a)(6)(B)(iii)
      • Requests investigation and deletion within FCRA timelines
  4. Outline a step-by-step action plan with deadlines to submit, follow up, and escalate to:
      CFPB → State Attorney General → FTC → civil litigation.

Use headings per item (e.g., "1. Charge-Off: Account #1234"). End with a checklist of next actions.Education, not legal advice.
The broke tax on a 72-month loan. Same car. Same everything.
Rates illustrative. Your rate depends on your profile and the market. The gap is real.
Balance ÷ limit × 100. Example: $300 ÷ $2,000 = 15%.
Act as my credit coach. My total limit is $____ and balance is $____. Build a 12-month plan to get my utilization under 15%, then under 10%. Give my target balance, the monthly payment, which card to attack first, and when to pay before each statement closes, as a month-by-month table.
How to get approved for $100K in funding
Bureau pulls vary by state, product and applicant and can change. Confirm before you apply.
Personal · establish first
Business · after entity
EIN only? Brex looks at the business, not your personal score. 0% is intro, not forever. Offers change.

Live forex and gold trading classes. Open the free trading group instructions below.
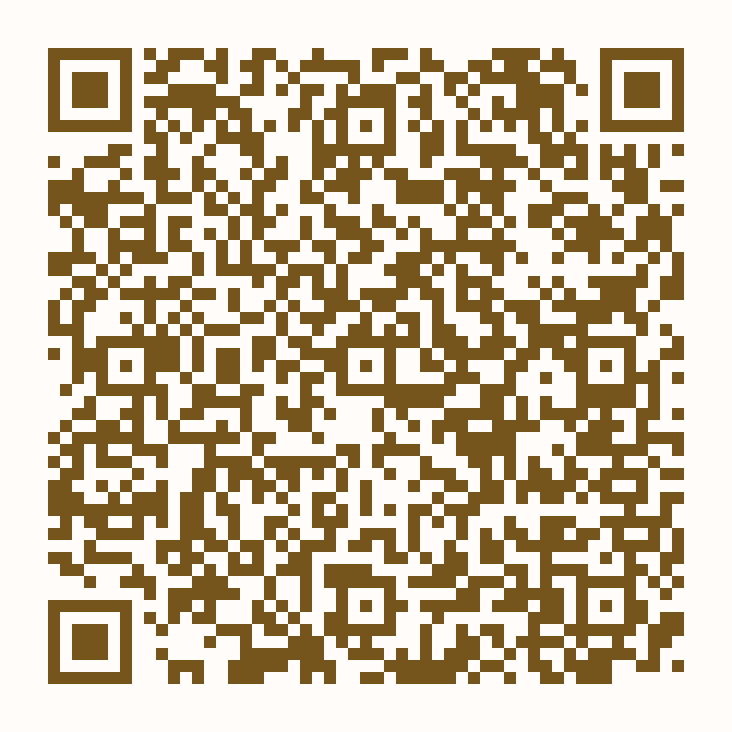 Scan or tap to join the free trading group
Digital product price: $97. The next slide breaks down the ad budget and sales targets.
Weeks 1–2: test at $100–$150/day. Weeks 3–4: scale winners to $400–$500/day.
Target model, not a guaranteed result. Revenue, not profit.
5 angles × 3 formats = 15 ads to launch. Add 3 new ads every week. Stop ads after $50 spent with no sale. Scale the ads that sell.

Sources: Wendor, VendBuddy and VendSoft 2026 price guides.
Flowers, candles, cards, flags and bottled water. Stock what families need when they visit. Partner with the cemetery.
What could 5 machines bring in?
5 × $80 per machine
5 × $300 per machine
5 × $600 per machine
Estimated startup for 5 machines: $10K–$35K.
Illustrative monthly net income estimates. Actual costs and results vary.

Plus car loss and damage, and cell phone insurance.
- Everything in Standard + Premium
- Aggressive done-for-you credit repair included
- 90-day funding roadmap built for you on a 1:1 kickoff
- Goal accountability private chat
- Funding application review before you apply
- CEO money management & budget strategy + business plan
On the next page, choose VIP — $697/year. The $19/month Standard plan is a separate option.
- Done-for-you credit repair options
- LIVE forex & gold trading
- 7-day consumer law training
- Funding application guidance
- Weekly LIVE coaching
No contract. Cancel anytime.
On the next page, choose Premium — $65/month. The $19/month Standard plan is a separate option.
Open the funding page to book your strategy call
Results shown are Princess Dior's own and her clients'. Individual results vary. Education, not legal or financial advice.